Dutch Banks and the 'Locked Funds' Dilemma: Choice or Coercion?
As the EU's Savings and Investments Union takes shape, Dutch financial institutions are offering citizens a stark choice: lock your savings away for years, or watch them stagnate. But is it a genuine opportunity, or a subtle form of pressure?
Amsterdam, September 1, 2026 – A quiet but significant shift is underway in the Dutch financial landscape. As the European Commission's ambitious Savings and Investments Union (SIU) moves from proposal to policy, Dutch banks are adapting their strategies—and the message to savers is becoming increasingly clear: parking your money in a traditional, instantly accessible savings account is no longer the smart move.
The numbers tell the story. According to De Nederlandsche Bank (DNB), Dutch households hold a staggering €535 billion in savings, with an even larger €1.6 trillion managed by pension funds. For years, this capital has sat in low-yield accounts at the "big three"—ABN AMRO, ING, and Rabobank—which typically offer interest rates of just 1.0% to 1.75% on standard savings accounts.
Now, those same banks, alongside a growing number of digital challengers, are aggressively pushing a different product: the term deposit. These accounts require savers to lock their money away for fixed periods—from three months to a staggering ten years—in exchange for higher, guaranteed returns.
The Incentive Structure: A Deeper Look
The message from Dutch banks is consistent: "flexibility is costing you money." The numbers appear to back this up. In the first half of 2026, deposit rates for long-term savings rose sharply. The average rate for a one-year deposit reached 2.22%, while five-year deposits offered 2.51%, and ten-year deposits hit 2.99%. Some banks are offering even more. Nexent Bank, for instance, advertises a 10-year deposit at 3.65% —a rate that far outstrips the 1.75% or less offered on instant-access accounts.
The message is not delivered with a direct "you must invest," but through a powerful economic incentive: "if you don't choose to lock away your money, you are actively choosing to lose purchasing power." As Olaf Sleijpen, President of DNB, framed it in a speech earlier this year, "money isn't meant to sit still". DNB has explicitly stated that it supports the SIU's ambition to "allocate more savings towards capital market investments" and to channel household savings into capital markets.
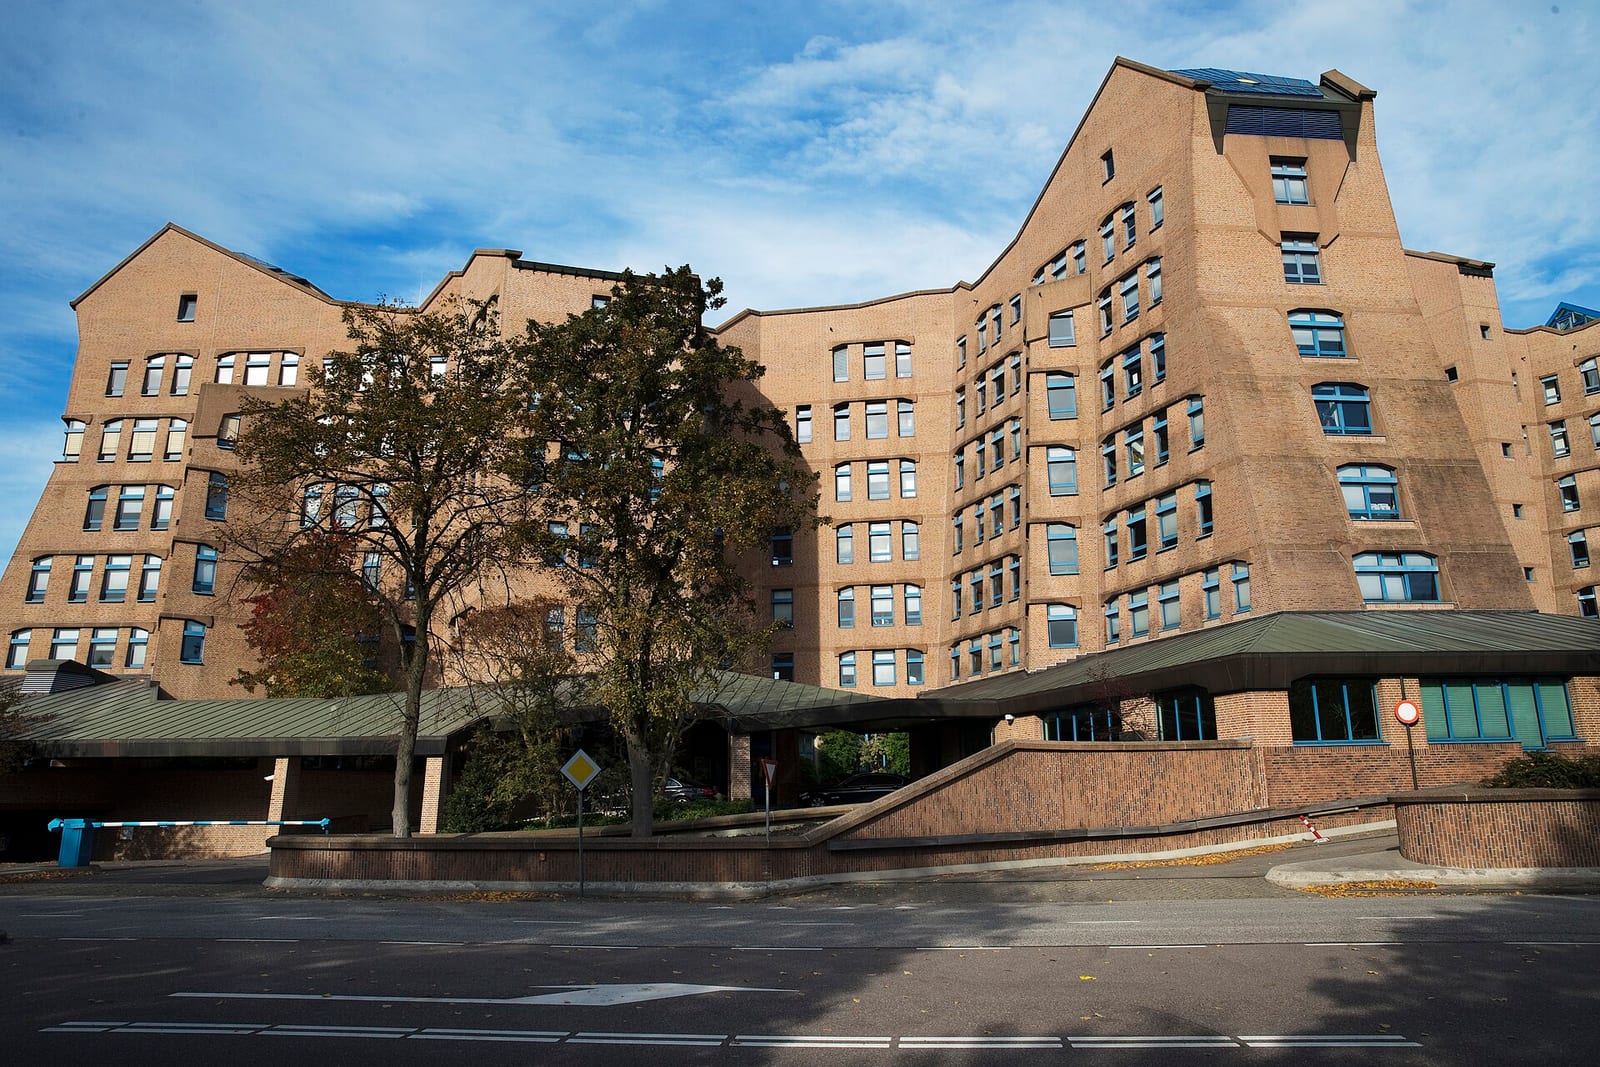 ING Bank headquarters at Amsterdamse Poort, Amsterdam. Photograph: public domain, via Wikimedia Commons
Choice, Coercion, and Control
The critical question for Dutch savers is where genuine choice ends and engineered coercion begins.
On one hand, the banks are simply responding to market conditions. Rising ECB rates and increased competition, particularly from digital players like bunq and foreign banks, have forced them to offer better returns. The deposit guarantee scheme (DGS), which protects savings up to €100,000 per person, applies to both instant-access accounts and term deposits, ensuring a baseline of security.
On the other hand, the timing and language are notable. DNB's President, Steven Maijoor, has openly stated that the Netherlands "stands to gain from a better functioning European capital market" and supports proposals to invest household savings more in equity. This is not neutral territory. Critics argue that the real goal is to turn "lazy" savings into "risk capital" for politically prioritized sectors, such as green energy and defense.
The distinction between "incentive" and "dwang" (force) is a fine one. As one commentator noted, the EU's plan is to use "soft pressure" to encourage banks and pension funds to invest in European bonds. For the average saver, this translates into a simple but stark choice: accept lower returns on accessible savings, or lock your money away for years to earn a more competitive rate.
An Open Question
The Dutch banking sector is not confiscating savings. But it is creating a financial ecosystem where the path of least resistance—keeping money in an instant-access account—is becoming increasingly unattractive.
The question for the individual saver is whether this represents a legitimate opportunity to build wealth or a slow-motion shift toward a system where the state, through its institutions, determines how your capital is deployed. As one academic put it, European citizens place a premium on the safety of their savings. The SIU, and the banks that support it, are betting that they can trade that safety for higher returns.
For now, the money remains yours. But the options available to you are being deliberately shaped. Whether that is a freedom or a constraint is ultimately for the individual to decide.
More from peatpost
Texas Court Dismisses Coinbase Shareholder Suit Over Delaware-Era Conduct
The Texas Business Court applied the state's written-demand rule after Coinbase reincorporated, even while assuming Delaware law governed the underlying claims.
Bullish and Equiniti Form Coalition for Issuer-Sponsored Tokenised Stocks
Alpaca, Apex Fintech Solutions and DriveWealth are early members of a group that wants tokenised shares to preserve the direct link between companies and their shareholders.
Qivalis Partners With Numeris to Build Settlement Rails for Its Euro Stablecoin
The Amsterdam-based banking consortium behind Europe's largest bank-backed euro stablecoin project has signed a multi-year collaboration with payments-infrastructure firm Numeris, covering settlement, reconciliation and merchant acceptance ahead of a launch planned for the second half of 2026.
Discussion
0 commentsNo comments yet — be the first to weigh in.