California Woman, 27, Extradited From Israel Sentenced to 8 Years in Prison for Global Online Fraud Scheme
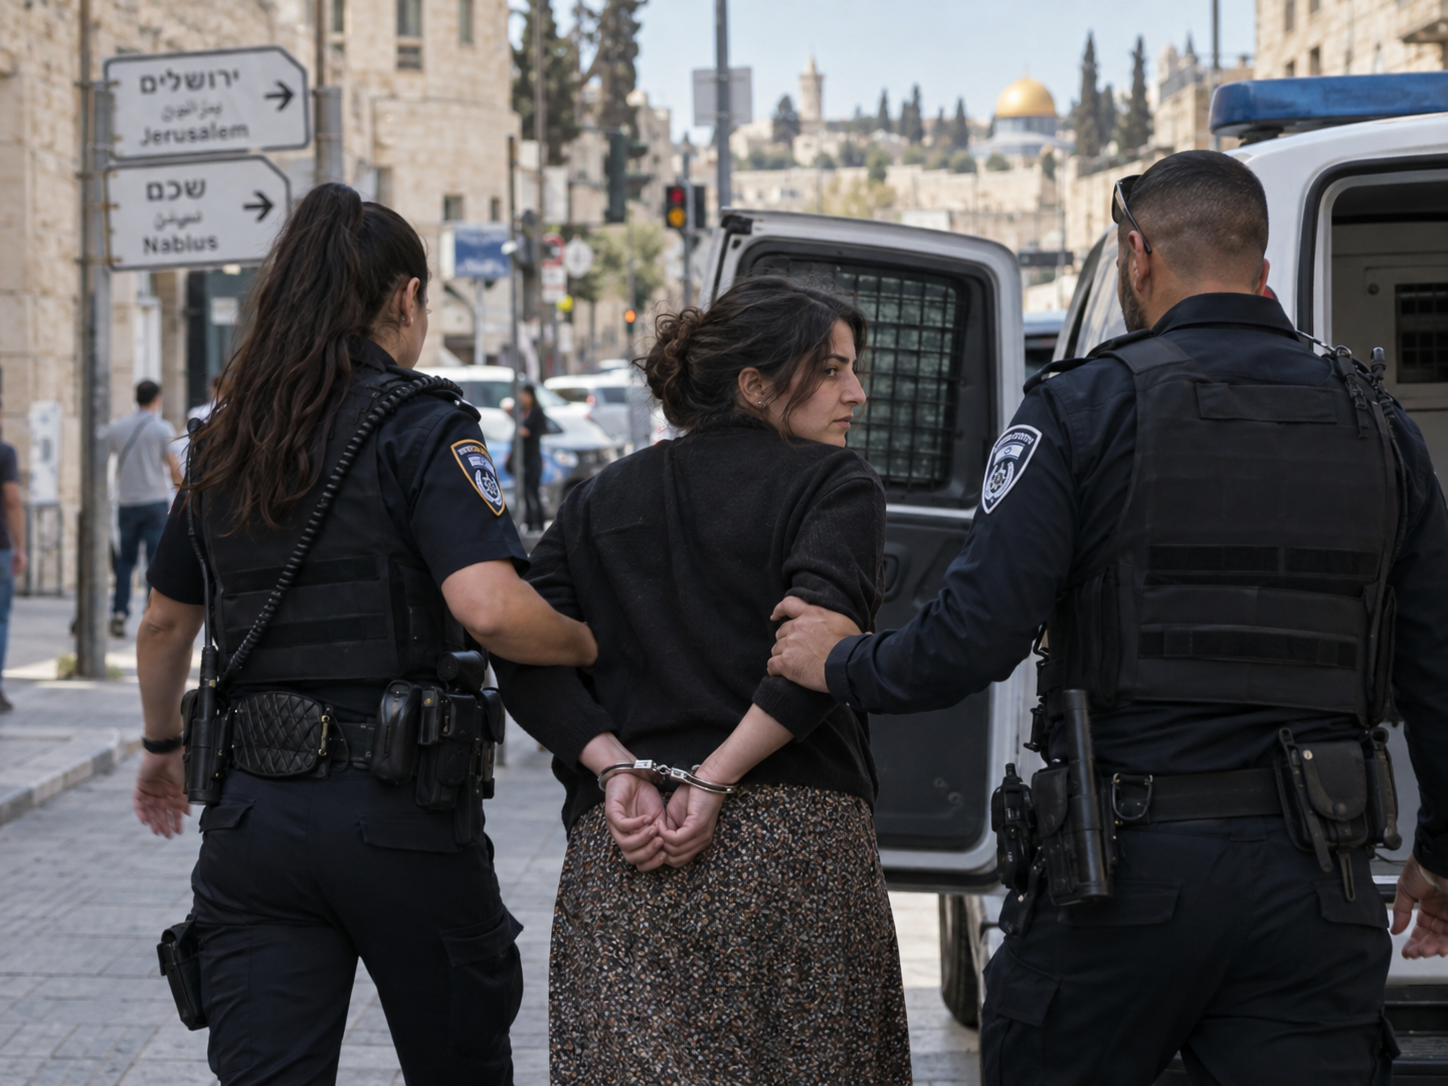
A federal judge on Tuesday sentenced a 27-year-old California woman to eight years in prison for orchestrating a sprawling online investment fraud scheme that prosecutors say victimized thousands of people worldwide, capping a years-long international investigation that ended with her extradition from Israel earlier this year.
Michelle Stone, 27, of Los Angeles, was sentenced by U.S. District Judge Margaret Ellison in the Central District of California after pleading guilty in June to one count of wire fraud and one count of conspiracy to commit money laundering. The sentence also includes three years of supervised release and an order to pay restitution of more than $47 million to identified victims, a figure prosecutors acknowledged is likely a fraction of the total losses.
The case drew international attention not only for the scale of the alleged fraud but for the trove of assets investigators say they uncovered upon Stone's arrest: ten cryptocurrency wallets stored on her smartphone, each containing approximately $2 million in stablecoins, and a portfolio of luxury real estate holdings in Dubai, Italy, the United Kingdom, and the United States, all allegedly purchased with illicit proceeds.
A Years-Long Scheme, a Sudden Arrest
According to court documents and statements made during the sentencing hearing, Stone began operating a network of fraudulent online trading platforms under various names in 2019, when she was just 20 years old. The platforms purported to offer automated cryptocurrency arbitrage and foreign-exchange trading services, promising investors consistent monthly returns of 8 to 15 percent. In reality, prosecutors said, the operations were a classic Ponzi structure: early investors were paid using funds from later investors, while Stone diverted millions of dollars into personal accounts and asset purchases.
Prosecutors described Stone as a sophisticated operator who, despite her youth, used multiple aliases, forged corporate documents, and created a veneer of legitimacy through fake regulatory registrations and fabricated audit reports. She allegedly targeted victims through social media advertising, paid influencer promotions, and direct outreach to retirees and small-business owners in the United States, Canada, Australia, and several European countries. Investigators said she presented herself online as an experienced financial professional in her forties, using filtered photographs and fabricated credentials to bolster the deception.
Stone fled the United States in late 2023 after a series of investor withdrawal requests went unmet and complaints began mounting with the FBI and the Securities and Exchange Commission. She was arrested by Israeli authorities in Tel Aviv in February 2025 at the request of the U.S. Department of Justice. Her extradition was approved by an Israeli district court in December 2025 after a lengthy legal battle in which her attorneys argued that she would face inhumane prison conditions in the United States. Israeli Justice Ministry officials confirmed at the time that the extradition order had been signed following a Supreme Court review.
The Phone and the Wallets
When Stone was taken into custody in Tel Aviv, investigators from the FBI's Los Angeles Field Office, working alongside Israeli police, obtained a warrant to search her personal effects. According to an affidavit unsealed in federal court in Los Angeles last week, a forensic examination of Stone's iPhone revealed ten separate cryptocurrency wallets, each holding approximately $2 million in stablecoins—primarily Tether (USDT) and USD Coin (USDC)—for a combined value of roughly $20 million at the time of seizure.
Prosecutors said the wallets were secured with biometric locks and were not linked to any of the corporate entities Stone had publicly disclosed. "These were not business accounts," Assistant U.S. Attorney Daniel Reyes said during the sentencing hearing. "These were personal slush funds, hidden behind encryption and accessed only by the defendant's face and fingerprint."
The stablecoin holdings have since been frozen by the U.S. Marshals Service pending forfeiture proceedings. Prosecutors indicated that additional cryptocurrency assets may exist in wallets that have not yet been accessed, and that the government is working with blockchain analytics firms to trace further transfers.
Real Estate Empire Under Scrutiny
Beyond the cryptocurrency, court records describe a global real estate portfolio that prosecutors allege was assembled using investor funds. The properties identified by investigators include:
A penthouse apartment in the Dubai Marina district, valued at approximately $4.2 million;
A villa in the Lake Como region of northern Italy, valued at roughly $6.8 million;
A townhouse in the Kensington area of London, valued at approximately $5.5 million;
An oceanfront condominium in Miami Beach, Florida, valued at $3.1 million;
A commercial building in downtown Los Angeles, valued at $7.4 million.
Prosecutors said the properties were held through a labyrinth of shell companies registered in Delaware, Nevada, Cyprus, and the United Arab Emirates. The government has filed civil forfeiture actions against all five properties, and a separate proceeding is underway in Dubai involving local authorities. Stone's defense attorneys have contested the forfeiture of the Miami condominium, arguing that it was purchased with funds from a legitimate real estate investment made before the alleged fraud began, but prosecutors described that claim as "not credible" in court filings.
Defense Paints a Different Picture
Stone's attorney, Sarah Kim of the federal public defender's office in Los Angeles, did not dispute the core facts of the fraud during sentencing but argued that her client had been a "middle manager" in a larger operation controlled by unnamed co-conspirators who remain at large. Kim said Stone had cooperated with investigators since her extradition, providing information about the structure of the scheme and the identities of several individuals who helped launder funds through foreign exchanges.
"Ms. Stone accepts responsibility for her conduct, and she has taken steps to assist the government in understanding the full scope of this operation," Kim told the court. "She was young and impressionable when this scheme began, and she was drawn into a criminal enterprise that was already underway. Once inside, she found it impossible to extract herself without facing threats to her safety and that of her family."
Kim requested a sentence of five years, citing Stone's youth, her cooperation, and what she described as "significant mental health challenges" that contributed to her decision-making. Judge Ellison rejected the request, noting that Stone had continued to solicit new investors even after learning that federal investigators had begun examining her activities, and that she had personally recruited some of the scheme's largest victims well into her twenties.
"You were old enough to know exactly what you were doing," Ellison said from the bench. "You knew people were losing their life savings, and you kept going. The fact that you were 20 when this started does not erase the seven years of harm that followed, and it does not explain why you were still doing it at 26."
Victims Describe Devastation
Several victims submitted impact statements that were read aloud in court. A 72-year-old retired teacher from Ohio wrote that she had lost her entire pension savings of approximately $340,000. A couple from Florida said they had invested the proceeds from the sale of their home and were now living in a rented apartment. A small-business owner from Australia submitted a statement saying that the loss had forced him to close his company and lay off twelve employees.
Several victims who attended the hearing in person expressed disbelief at Stone's age. "She sounded so professional on the phone, so experienced," said one victim, a 61-year-old from Texas who asked not to be named. "To find out she was a kid in her twenties the whole time—I still can't process it."
The full number of victims is unknown, but prosecutors said they have identified more than 1,800 individuals across at least fourteen countries who transferred funds to accounts controlled by Stone or her associates. The FBI has established a victim assistance hotline and is encouraging anyone who believes they were defrauded to come forward.
A Growing Pattern of Cross-Border Crypto Fraud
Stone's case is among a growing number of prosecutions involving suspects who flee to jurisdictions with complicated extradition relationships with the United States. Israel, which has an extradition treaty with the U.S. dating back to 1963, has in recent years extradited several individuals accused of financial crimes, including a high-profile case involving a former CEO of a binary options firm who was ultimately sentenced to 22 years in prison in Maryland.
Legal experts say the Stone case illustrates both the promise and the difficulty of international law enforcement cooperation in the cryptocurrency era—and raises unsettling questions about how early in life sophisticated financial fraud can begin. "The blockchain leaves a trail, but the moment assets move into stablecoins and then into real estate, the tracing becomes exponentially more complex," said Rebecca Torres, a former federal prosecutor who now teaches at Georgetown Law. "What made this case work was the phone. If she had used a hardware wallet or left the phone behind, we might be having a very different conversation."
Torres added that Stone's age makes the case unusual but not unprecedented. "Young people understand this technology intuitively," she said. "That cuts both ways."
Stone is expected to be transferred to a federal correctional facility in the coming weeks. Because of her age and the length of her sentence, she will be in her mid-thirties upon release if she serves the full term. Her attorney has indicated she intends to appeal the restitution order, though not the conviction or the prison sentence. A separate civil case brought by the SEC against Stone and several unnamed associates is pending in federal court in Los Angeles.
The FBI's investigation remains active, and prosecutors said additional charges against other individuals are possible. "This is not the end of the story," Reyes said outside the courthouse. "There are people who helped Ms. Stone, who facilitated the movement of funds, who provided the infrastructure for this scheme. We are not done."
More from peatpost
Bitcoin Steadies Near $76,000 as Analysts Read Bullish Signals in Quiet Trading
After an AI-driven sell-off, bitcoin is trading in a 0.4% daily range. Two chartists see a rebound setup, though one expects any rally to end badly.
Anthropic Study Finds Analysts Followed AI Agent's Hidden Lean on 86% of Key Judgement Calls
In a controlled test, 50 expert analysts largely adopted an AI agent's secretly assigned preference, and none suspected it had been planted.
ESMA Tells EU Crypto Firms to Stop Services Involving Non-Compliant Stablecoins
The regulator's 8 October opinion reaches well beyond trading pairs, covering custody, transfers, advice and portfolio management for tokens outside MiCA rules.
Discussion
0 commentsNo comments yet — be the first to weigh in.